The Quiet Migration of Data Away From Big Cloud
Why governments and businesses are pulling data back from global cloud providers to sovereign local alternatives.

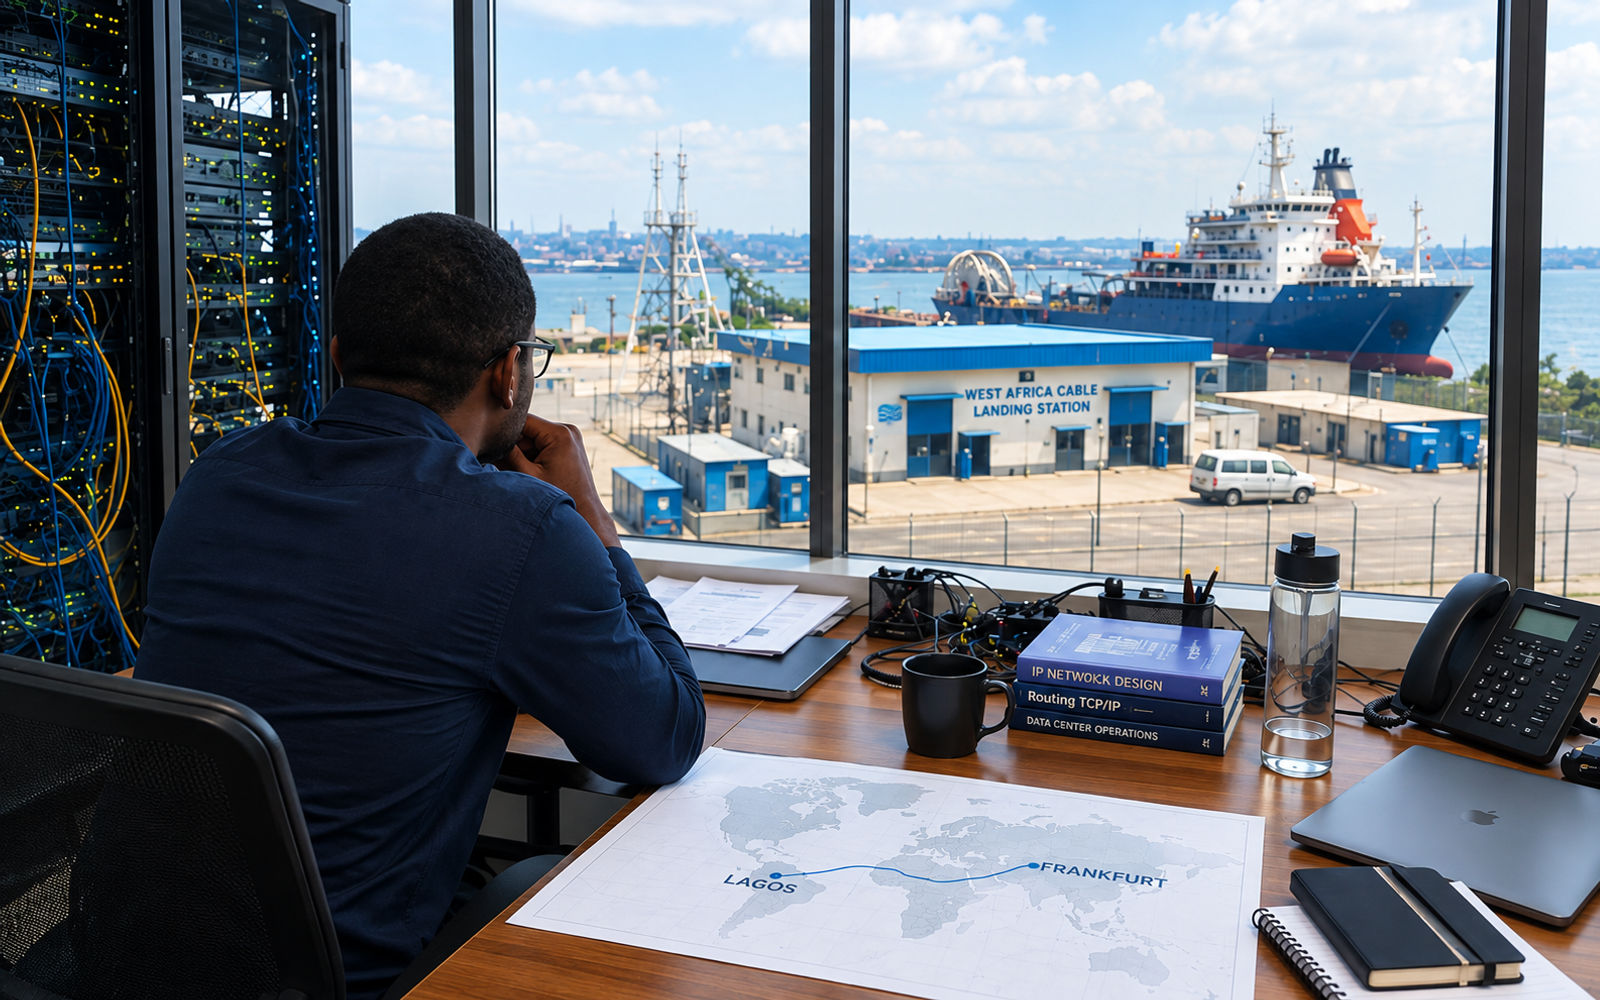
The round-trip time for a data packet between a financial terminal in Lagos and a cloud server in Frankfurt sits around 115 milliseconds, give or take the whims of traffic on the SAT-3 undersea cable. That delay doesn't sound severe until you factor in the way modern application stacks work. A single API call to process a mobile money transaction can require six, eight, sometimes twelve round trips between client and server. Multiplied across millions of transactions daily, that latency stops being a technical footnote and becomes a structural cost. It's the physics of distance, pure and simple. Light in fiber moves at roughly two-thirds the speed of light in a vacuum. You can't negotiate with that number. You can only shorten the path.
This is the constraint quietly reshaping the cloud computing industry in 2026, and it has a name most consumers have never heard. Geopatriation. The deliberate, sometimes mandated relocation of data and applications away from global public cloud platforms toward sovereign local alternatives. According to All Covered's analysis of cloud trends for 2026, geopatriation stands as the single most consequential shift in enterprise infrastructure strategy this year. Not because the big cloud providers lost any technical edge. The reason is more structural. The assumptions that made global public cloud attractive are grinding against the physical realities of distance, the regulatory demands of national governments, and a creeping recognition that control of data infrastructure is control of economic destiny.
The Physics That Broke the Global Cloud Promise
The original pitch for public cloud was seductive in its simplicity. Hand your data to the big providers, and they'd handle the rest. The economics of scale were so lopsided that no single company could match the unit costs. For a decade, that math held. But the math didn't account for what happens when data crosses borders. Every time a packet leaves Nigerian jurisdiction to hit a server in Europe, it passes through legal territory that's increasingly hostile to unregulated data flow. Nigeria's Data Protection Regulation, Kenya's Data Protection Act, Ghana's Data Protection Act, all impose restrictions on cross-border data transfer. The European Union's GDPR was the template. Now there are dozens of national variants, each with its own enforcement teeth.
The compliance burden has inverted the cost calculation. According to Shapeblue's analysis of cloud trends for 2026, VMware licensing disruption remains the largest trigger for cloud strategy change. When Broadcom acquired VMware in late 2023 and restructured its licensing model, eliminating perpetual licenses and pushing all customers into subscription arrangements, enterprise customers saw their infrastructure costs spike unpredictably. That shockwave is still propagating. Companies that had bet their entire cloud architecture on VMware's ecosystem suddenly faced a choice. Absorb the new pricing or rebuild on something else. Many chose to rebuild, and in that rebuilding, they're asking a question they hadn't asked in years. Where should this data actually live? The answer increasingly points to local infrastructure, not distant data centers.
A Word That Describes a Movement
Geopatriation is an ungainly word for an elegant shift. It combines geo and repatriation, and what it describes is companies pulling workloads back from faraway cloud regions and placing them on local infrastructure. Not on-premises in the old sense, necessarily. Local can mean a sovereign cloud operated by a domestic provider, a colocation facility in the same city, or a government-regulated national cloud. The common thread is that the data stops traveling long distances. Gartner has identified geopatriation as a defining enterprise trend for 2026, forecasting sovereign cloud infrastructure-as-a-service spending to reach $80 billion, a 35.6% increase from 2025. That's not pocket change. That's a structural reallocation of capital.
This is not a fringe trend driven by paranoia. It's a structural response to measurable problems. The public cloud model optimized for cost per gigabyte of storage. It did not optimize for latency per packet of real-time data. It did not optimize for regulatory clarity. And it certainly did not optimize for national economic sovereignty. Put differently, the public cloud was designed for the world of batch processing and file storage. That world is shrinking. The world of real-time inference, sensor networks, and cross-border data regulation is growing. And that world demands local infrastructure.
The European and African Parallel Tracks
Europe moved first on geopatriation, partly because GDPR gave it no choice. Germany's Sovereign Cloud Stack initiative, France's national cloud certification program, the Netherlands' push for government data to stay on Dutch infrastructure. These aren't anti-American moves in any technical sense. German cloud providers use plenty of American hardware and software. But the control plane, the governance layer, the data residency guarantee sits with local entities. The architecture is the same. The jurisdiction is different. That distinction matters more than most architectural decisions.
Africa is moving faster than most outsiders realize. In Nigeria, the push for data localization has accelerated alongside the growth of the country's fintech sector. Companies like Flutterwave and Paystack, both processing billions of dollars in transactions, cannot afford to have their transaction data routed through foreign servers. The latency alone would break the user experience. Mobile money works because it's fast. Every extra millisecond is a customer friction point. In March 2026, Tetracore Energy Group announced plans for a $400 million, 20-megawatt gas-powered data center in Nigeria, signaling that the infrastructure buildout is moving from planning into construction.
Kenya's Silicon Savannah offers a parallel story. Safaricom's data center in Nairobi, along with several colocation facilities operated by providers like Icolo.io and Africa Data Centres, have expanded capacity specifically to serve local workloads that previously traveled to Europe. The cost of these local facilities remains higher per unit than AWS's Frankfurt region. But when you factor in the avoided latency, the regulatory compliance certainty, and the elimination of cross-border data transfer taxes, the local option wins on total cost of operation. That math gets more favorable every year.
The VMware Trigger Nobody Planned For
The Broadcom acquisition of VMware deserves its own accounting because it functioned as a forced migration event. VMware's virtualization stack was the foundation of countless enterprise cloud architectures. When Broadcom raised prices and changed licensing terms, the cost impact hit budgets hard. Companies started looking at alternatives. Some moved to open-source virtualization platforms like KVM or Proxmox. Others shifted workloads to different cloud providers entirely. But the most interesting response was the companies that used the disruption as an excuse to rethink where their data lived geographically.
This is the hidden second-order effect. The immediate story was about rising costs. The longer story is about a wave of infrastructure redesigns that happened under cost pressure, and those redesigns embedded geographic sovereignty into the architecture from the start. Once a company has rebuilt its data pipeline to run on local infrastructure, the switching cost to go back to a global public cloud is just as high as the switching cost that pushed them out of it. The migration is sticky in both directions. Sovereign local alternatives are now competing directly with global public clouds not just on compliance grounds but on performance grounds, particularly for latency-sensitive workloads. The VMware disruption accelerated a timeline already moving in this direction.
What Serverless and Edge Bring to the Picture
Serverless architectures, where code runs in stateless containers that scale automatically, have become a natural fit for the geopatriation trend. The reason is straightforward. Serverless functions are small, portable, and easy to move between cloud environments. A company running its customer authentication layer on AWS Lambda can, with moderate engineering effort, migrate that same logic to a local cloud provider's equivalent service. The abstraction layer that serverless provides lowers the switching cost between providers, which is exactly what makes geopatriation feasible for companies that don't have massive engineering teams.
Edge computing pushes the same logic further. Instead of centralizing compute in a few massive data centers, edge distributes it across many smaller nodes located near where data is generated. For applications like agricultural sensor networks in rural Kenya, autonomous vehicle coordination in Shenzhen, or real-time fraud detection in London, the edge isn't optional. It's the only architecture that meets the latency requirements. The connection between edge computing and geopatriation is that edge nodes are inherently local. Every edge deployment is, by definition, a sovereign deployment.
Shenzhen offers a useful counterpoint to the African examples. China's cloud computing market has always been sovereign by default, constrained by the Great Firewall and domestic regulatory requirements. Alibaba Cloud and Tencent Cloud dominate not because they're technically superior to AWS but because they're inside the jurisdiction. The Chinese model shows what happens when geopatriation is mandated rather than chosen. The infrastructure is robust, the latency is low, and the local providers have achieved massive scale. But the ecosystem is also closed, with limited interoperability and high switching costs for customers who might want to participate in global markets. Sovereignty has tradeoffs, and China's approach makes them explicit. This dynamic of concentrated market power in infrastructure isn't unique to cloud computing, of course. NovaRift has previously covered similar patterns in other sectors where a few dominant players control critical infrastructure and the pricing power that comes with it.
The Question Nobody Has Answered Yet
The big question lurking beneath the geopatriation trend is whether local clouds can match the pace of innovation that the global public clouds deliver. AWS, Azure, and Google Cloud spend tens of billions of dollars annually on research and development. They roll out new services at a rate measured in weeks, not quarters. A sovereign cloud provider in Lagos or Nairobi cannot replicate that investment scale. What it can do is offer the services that matter most to its customers, run them reliably, and keep the data inside the borders where it's regulated. That's a narrower value proposition, but for many workloads, it's entirely sufficient.
Gartner's data shows Europe and China as the top spending regions for sovereign cloud, together accounting for the vast majority of the $80 billion market. But the growth rates are highest in regions where the infrastructure is still being built. East Africa has around 100 megawatts of new data center capacity in various stages of development, slated to come to market by 2030. That's not trivial. That's the electrical equivalent of a small power plant, dedicated entirely to local compute.
The global cloud providers are responding to the geopatriation trend by building local regions in more countries. AWS has added locations in South Africa, India, and the Middle East. Azure has expanded its sovereign cloud offerings. The big providers understand that if they don't offer local control, their customers will find someone who does. So they're adapting, building local infrastructure that offers the same global platform but with local data residency. Whether that's enough to reverse the momentum depends on whether customers trust the global providers to maintain local control over the long term, or whether they'd rather own the infrastructure themselves.
That's the open question. The data centers are getting built. The cables are getting laid. The regulatory frameworks are taking shape. But nobody has yet solved the problem of how a small sovereign cloud ecosystem keeps up with the global frontier of cloud innovation without turning into a satellite of the very providers it moved away from. That tension defines the cloud industry in 2026. It will define the next decade after that.
Comments (0)
No comments yet. Be the first to share your thoughts.